mobile domain:www.usaa.com
Skip to Content

Budgeting tips to help you take control of your money

Take control of your finances with these helpful budgeting tips so you can save for the future and work towards financial security.

Article: 8 minutes

Updated: September 15, 2026 Published: October 12, 2022

By: USAA Reviewed by: Editorial contributors

Summary

Budgeting doesn't have to be complicated. By focusing on simple, practical ways to manage your money, you can provide for your everyday expenses while ensuring you're setting aside enough for long‑term goals like retirement.

Key takeaways

  • Focus on the purpose of budgeting: The main goal is to effectively manage your money so you can meet your financial goals and responsibilities.
  • Avoid overcomplicating your finances: You don’t need detailed spreadsheets or rigid tracking as simple systems are often more effective and easier to stick with overtime.
  • Use guideline-based spending plans: Approaches such as the 20/50/30 rule (20% savings/debt, 50% needs, 30% wants) is a great place to start.

Some people enjoy the process of making a spending plan or budget. They enjoy using spreadsheets to track their income and listing out all their expenses. They like the discipline and accountability.

But many people don't enjoy that structure. They may be wondering, "What's the point".

What's the point of budgeting?

It's actually pretty simple, Imagine a squirrel putting away acorns for winter. In a nutshell, that's why we budget.

Instead of saving for winter, we're saving for the future while making sure we have enough for today. We make a budget so we don't forget about putting aside money for later, when we are no longer working. What about our income and expenses? What about slicing and dicing so we have money to eat out, go to the movies, pay for our kid’s college and pay down debt?

To guide your spending, most of us need some type of budget. But if you feel overwhelmed and you want to streamline it as much as possible, you can use the principles of budgeting to be sure you're saving enough for long term goals like retirement. Then you can spend the rest.

Save for immediate and future needs.

A lot of people don't like budgets, but they still want to be sure they're saving enough for future financial needs, such as retirement or for an emergency fund. For the budget wary, the 20-50-30 rule, a general spending plan framework. The 20-50-30 rule means that 20% goes to savings or paying down debt, 50% of your money goes to needs, and 30% goes to wants.

In the interest of keeping things simple, consider Jackie, a recent college graduate fortunate enough to enter the job market with no debt. She just landed a job that pays $50,000 a year.

Of course, starting with a blank slate is not realistic but it helps us illustrate the point, and once you get the point, you can apply it to different scenarios.

Jackie's first move should be saving for emergencies and retirement. And according to the 20-50-30 rule, she should put 20% or about $833 per month away.

That means some of the $833 can go to her employer-provided retirement savings plan — such as a 401(k), Thrift Savings Plan or 403(b), especially if she's eligible to receive matching contributions. Jackie should ask her employer to automatically deposit that money into her retirement plan account, so she never sees it hit her checking account. The other portion can go into an emergency savings fund, which can be automatically deposited into a dedicated savings account.

Be sure your needs are met.

If you're like Jackie and you're already saving 20% of your paycheck, take a minute to congratulate yourself. You've become one with that squirrel, and you haven't even had to put pen to paper.

Since you're on a roll, let's keep going. In the 20-50-30 rule, 50% of your income goes toward needs, which include all your essential expenses.

With Jackie's $50,000 salary, she has about $2,000 a month to spend on essentials. Essentials include expenses like mortgage or rent, utilities, property taxes, groceries, car payments, and gas.

Then have some fun — now and later.

Now for the fun part! The 20-50-30 rule allows 30% of your money to go toward things you want.

If you're already socking money away for needs like retirement and you're covering your essential living expenses, everything else is yours to spend guilt-free.

You probably don't need help coming up with items for your wants bucket, but it includes things you could live without, such as club memberships, dining out, streaming services, etc.

As you spend money on the fun stuff, consider setting some aside for more fun later. If you start saving now for your summer vacation or holiday gifts, you'll feel a lot more festive once these occasions arrive — not to mention after they're over.
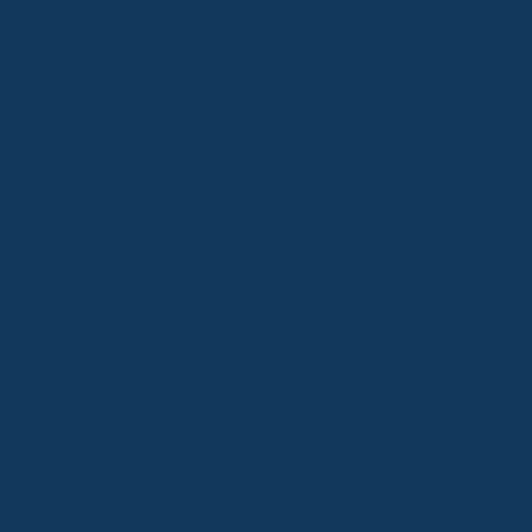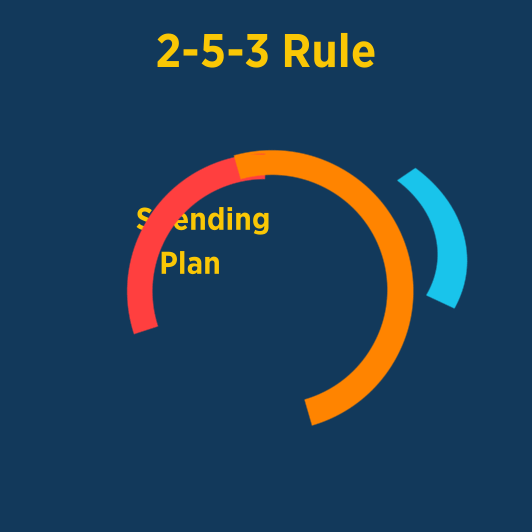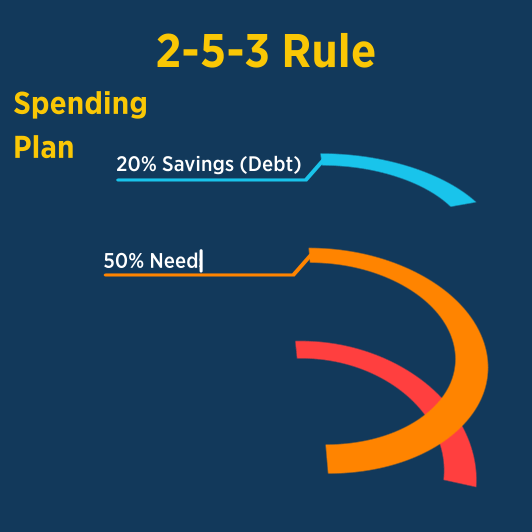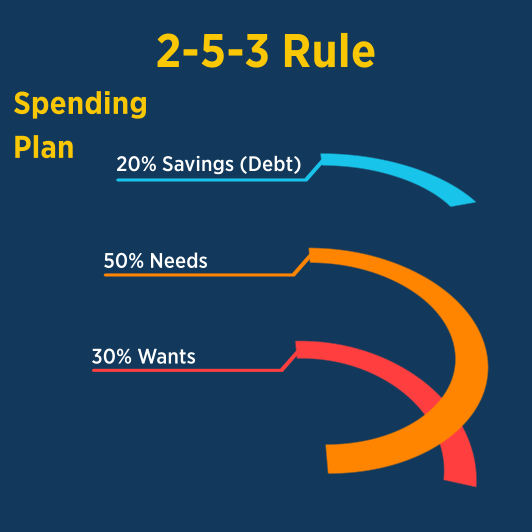
Animated gif explaining 2-5-3 rule which states 20% of income should go toward savings or paying off debt, 50% should go toward needs and 30% should go toward wants.

Video Duration:

Balance saving for emergencies and retirement and paying off high-interest debt.

Unlike Jackie, most people don't have the luxury of starting with a blank slate when they make a budget. Life is complicated, and we get backed into circumstances that have ripple effects on our finances.

For example, maybe when you bought your house, you could afford your mortgage. You didn't anticipate that your company would downsize. Or maybe you have so much student loan debt that even the thought of a mortgage — much less saving 20% of your money — is laughable.

That's OK. The 20-50-30 rule is flexible, if you understand what goes into each bucket.

We've said that it's important to save 20% of your income for your immediate or future needs. There's one exception to that rule, and that is debt repayments.

Let's go back to our example with Jackie. Imagine that instead of starting with a blank slate, she has accumulated $20,000 of high-interest credit card debt.

Jackie really wants to save for her retirement, but she also wants to get out of debt. And she knows that her debt is snowballing. With a 16% annual percentage rate, she's paying $3,200 in interest every year — assuming no new charges on the card and the current payment she makes is enough to keep the balance from growing each month. And she knows that if she could just pay that money off, she could save so much more for retirement.

What should she do? The important thing is for Jackie to first, stop adding to her debt, and second, get in the habit of paying down her debt.

After two years, if Jackie increases her debt payments, she could have her debt paid off. She'll also be in the habit of putting money away. And now that her debt is paid off, she can turn her attention toward her retirement and other goals.

What does savings really mean?

We've said that the 20% savings bucket refers specifically to saving for emergencies or retirement or, in the near term, paying down high-interest debt.

But what about the money we want to save for our kid’s college? Or the money we're putting aside for a down payment on a new home? Aren't all these savings goals too?

Technically, these things are considered wants. It may be an important goal for you and your spouse to fund your children's college, but remember that there are other ways available to help pay for tuition by using loans and scholarships. There are no scholarships or loans to fund your retirement.

Finally, it’s important to communicate with your spouse or partner so you're both on the same page when it comes to understanding your needs and prioritizing your wants. Most people's essentials — mortgage or rent, utilities, car payment — are fairly consistent other than changes to insurance premiums or property taxes. It's the nonessentials you want to spot-check with each other to be sure you aren't going into debt.

Simplify your finances

USAA offers helpful personal budgeting tools.

Get started with USAA’s personal budgeting
tools

Related articles

How to create a budget: Lessons from being broke

Article: 5 minutes

Read article: How to create a budget: Lessons from being broke

Psychology of budgeting: How to budget like a pro

Article: 6 minutes

Read article: Psychology of budgeting: How to budget like a pro

Money-saving tips to reach your financial goals

Article: 3 minutes

Read article: Money-saving tips to reach your financial goals

Related footnotes:

  1. This material is for informational purposes. Consider your own financial circumstances carefully before making a decision and consult with your tax, legal or estate planning professional.

Related footnotes:

  1. USAA means United Services Automobile Association and its affiliates.

5857303